 Eski Pano
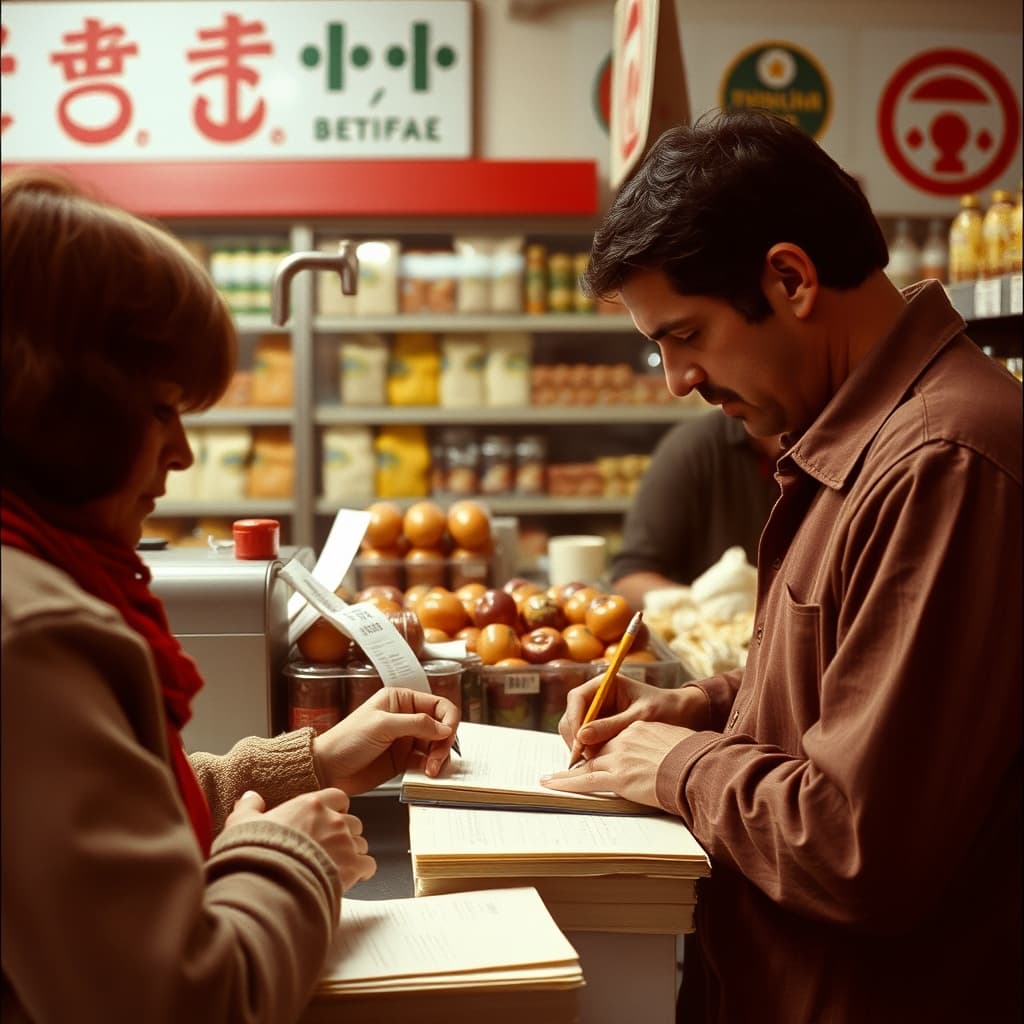
A neighbourhood credit ledger is often remembered as proof that trust once replaced paperwork. The ledger itself shows that trust was written down: names, dates, goods, amounts, repayments, corrections, and balances created a record with economic and personal consequences. Reading it warmly does not require ignoring debt, error, embarrassment, unequal bargaining power, or the privacy of families whose purchases remain visible decades later.
Informal credit varied by trade, district, period, currency, inflation, regulation, income pattern, and relationship. A grocer's running account, baker's tally, pharmacist's debt, cooperative book, employer advance, and supplier ledger were not identical. Surviving pages should be studied with price lists, receipts, shop records, oral histories, consumer law, and the accounts of both sellers and customers.
Every Entry Was an Accounting Claim
A reliable entry needed a date, identifiable customer, goods or reference, quantity, price, payment, and remaining balance. Abbreviations understood by one shopkeeper can become ambiguous later. Crossed-out figures, overwritten totals, transferred pages, torn receipts, rounding, currency changes, and mental arithmetic create errors. Trust did not eliminate the need for reconciliation.
Customers should have been able to know the balance and challenge a mistake without humiliation. A signature, duplicate slip, periodic total, witnessed entry, or separate customer notebook could reduce disputes. Children sent to collect goods should not be pressured to confirm debt, carry sensitive messages, or accept changed terms they cannot understand.
Credit Terms Needed Fair Boundaries
Some accounts carried no explicit interest, while price timing, fees, late charges, compulsory purchases, or different cash and credit prices could still affect cost. The absence of a formal contract did not guarantee fairness. Modern lending and consumer-protection rules vary by jurisdiction and may apply to repeated commercial credit. Nostalgia is not legal advice or permission to recreate unregulated debt.
A seller faced genuine risk from unpaid balances and volatile wholesale prices. A household faced irregular wages, illness, seasonal work, school expenses, or emergency need. Ethical history should show both pressures without turning poverty into neighbourly charm. Clear limits, transparent prices, affordable repayment, and referral to appropriate support protect relationships better than indefinite obligation.
The Ledger Contains Sensitive Personal Data
Purchases can reveal health, religion, diet, pregnancy, alcohol use, household size, financial distress, absence from home, or political activity. Names, addresses, family links, and handwriting may identify living people. An archive should assess legal basis, retention, access, redaction, anonymisation, consent, and research value before publishing scanned pages.
Digitisation should preserve page order, covers, numbering, corrections, paper condition, and links to related receipts while controlling access. Searchable transcription increases research value but also makes private information easier to discover. Public versions may need delayed release or redaction, while restricted originals retain evidence under documented governance.
Current digital tabs, loyalty systems, messaging, and delivery platforms can collect more information than the old notebook. Security, role-based access, backups, deletion schedules, breach response, and customer rights matter. A photograph of a ledger should never be shared casually in a group chat simply because the book looks historic.
A Digital Nostalgia Archive can connect the ledger with shop context, accounting method, price changes, repayment practices, customer testimony, dispute examples, data assessment, redaction decisions, and retention policy. Trust was present, but it was not a substitute for accurate accounts and dignity. Preserving the warmest scene of local credit means protecting both sides of the counter through fairness, privacy, transparent limits, and the right to correct the record.